The “high uncertainty” of the global context – with two conflicts and geopolitical tensions – “slightly worsens” the prospects for inflation “in the short term” and requires Italy to strengthen the resilience of the country’s energy and defense system. “Energy markets remain under pressure and the gradual recovery of oil and gas prices is slower than expected”, notes the government in the Prime Ministerial Decree approved on Friday 2 October in the Council of Ministers and sent to the Chambers.
The document revises growth upwards to 1% for 2026 while the deficit/GDP ratio stands at 2.9%. The MEF simulations, in the most adverse scenario, assume a loss of 0.3% of GDP between 2027-2028 with the continuation of the energy shock underway with the conflict in the Middle East.
The difference from almost 29 billion for energy and defense
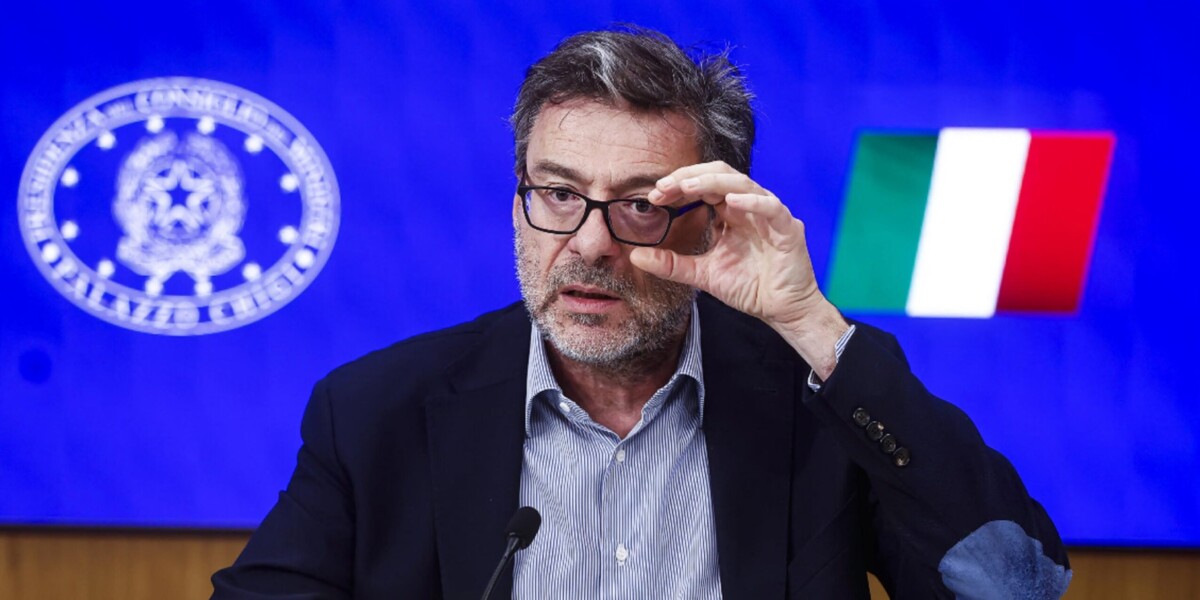
For this reason, Giorgia Meloni’s executive has asked Parliament to approve a budget deviation of almost 29 billion euros (0.3% of GDP for each of the two sectors) for the two-year period 2027-2028, within the flexibility agreed with the EU. For families and businesses, we are thinking of 14.4 billion in energy interventions, with investments in renewables and measures to encourage the use of public transport by students. On defence, however, the program envisages interventions on personnel and investments, as part of the commitments undertaken within NATO. The vote in the House on the deviation proposal is expected on October 13th. In light of this scenario, the government is preparing, warns Economy Minister Giancarlo Giorgetti, for a “more prudent” maneuver compared to the spending hypotheses that have circulated in recent weeks.
Estimates and exit from the EU procedure
The Public Finance Policy Document outlines an update of the macroeconomic estimates in light of the changes in the global scenario, which takes into account a “restrictive orientation of monetary policy” which has been “associated with an increase in the yields of public securities”, resulting in “less favorable financial conditions”. However, the text also identifies favorable conditions for Italy to exit the EU excessive deficit procedure in 2027. And it outlines the “favorable moment” experienced by the labor market for which “wide margins for growth remain”. Furthermore, the need for a correction of the accounts in 2027 is excluded, while the possibility of a moderately expansionary maneuver in 2028 and 2029 is hypothesized. It is also underlined that in recent years the production system “has shown a greater ability to adapt to external shocks”.
The numbers of the DPFP: deficit, growth and debt
The programmatic scenario foresees: net debt including the use of the NEC at 3.4% for 2027, 3.2% for 2028 and 2.3% in 2029. Net debt excluding the use of the NEC: 2.8% for 2027; 2.6% for 2028 and 2.3% in 2029.
In the following years, the programmatic GDP growth rate stands at 0.8% in 2027, 0.9% in 2028, 0.8% in 2029. Programmatic public debt expected: 138.1% at the end of 2026; 138.5% in 2027, drops to 137.9% in 2028 and 136.6% in 2029.
The temporary increase in debt compared to 2025, with an expected peak for next year at 138.4%, is due “largely to the cash impact of tax credits connected to construction bonuses, which is expected to be at its maximum this year”.
Tax pressure and revenue
The tax burden (43.0%) will “increase very slightly” compared to 2025 (0.1%), with a “decisive contribution” provided by efforts aimed at combating tax evasion, including through the promotion of tax compliance. Tax revenues will grow in 2026 in line with nominal GDP, as a result of a “slightly lower growth in direct taxes (+2.5%)” and a “very dynamic” growth in indirect taxes (+3.2%), which will also be driven by the expansion of VAT revenue.
Inflation, interest and pension spending
Interest expenditure in 2026 “is mainly affected by the trend of inflation” and, in subsequent years, “incorporates the effects of the rise in yields observed on the government bond markets and the consequent upward shift in rates”. The other components of current expenditure “record generally more limited variations”. However, some items, in particular pension spending, “are affected by the new inflation profile”.
The job market
The analysis of the transitions between employment, unemployment and inactivity confirms “the favorable phase of the evolution of the labor market”. The increase in transitions from inactivity towards job search and employment, together with the reduction in the duration of inactivity, “signals a strengthening of participation and a more intense involvement of the population in the labor market”. Despite the progress achieved in recent years, “there remains ample room to increase participation in the labor market”.